Why should I choose AnalystNotes?
AnalystNotes specializes in helping candidates pass. Period.
Basic Question 1 of 17
Refer to the following price-yield curve.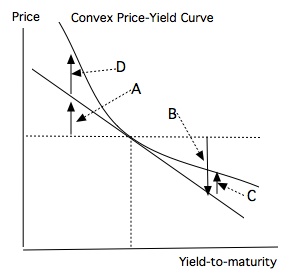
The estimated changes due to duration are represented by ______.
User Contributed Comments 2
| User | Comment |
|---|---|
| msusolar | can anybody explain? |
| CFAMay2022 | A&B reps changes in price due to change in YTM/slope of the tangent line (rather than actual changes on curve) |
I just wanted to share the good news that I passed CFA Level I!!! Thank you for your help - I think the online question bank helped cut the clutter and made a positive difference.
Edward Liu
Learning Outcome Statements
calculate and interpret convexity and describe the convexity adjustment
calculate the percentage price change of a bond for a specified change in yield, given the bond's duration and convexity
CFA® 2026 Level I Curriculum, Volume 4, Module 12.